EDPMS & IDPMS: Complete Guide for Indian Importers and Exporters (2026 Update)
EDPMS and IDPMS for Indian importers and exporters: BOE-ORM matching, FEMA 2026 timelines, ₹10 lakh declaration closure and services entries
Listen to article
Audio version (0% complete)
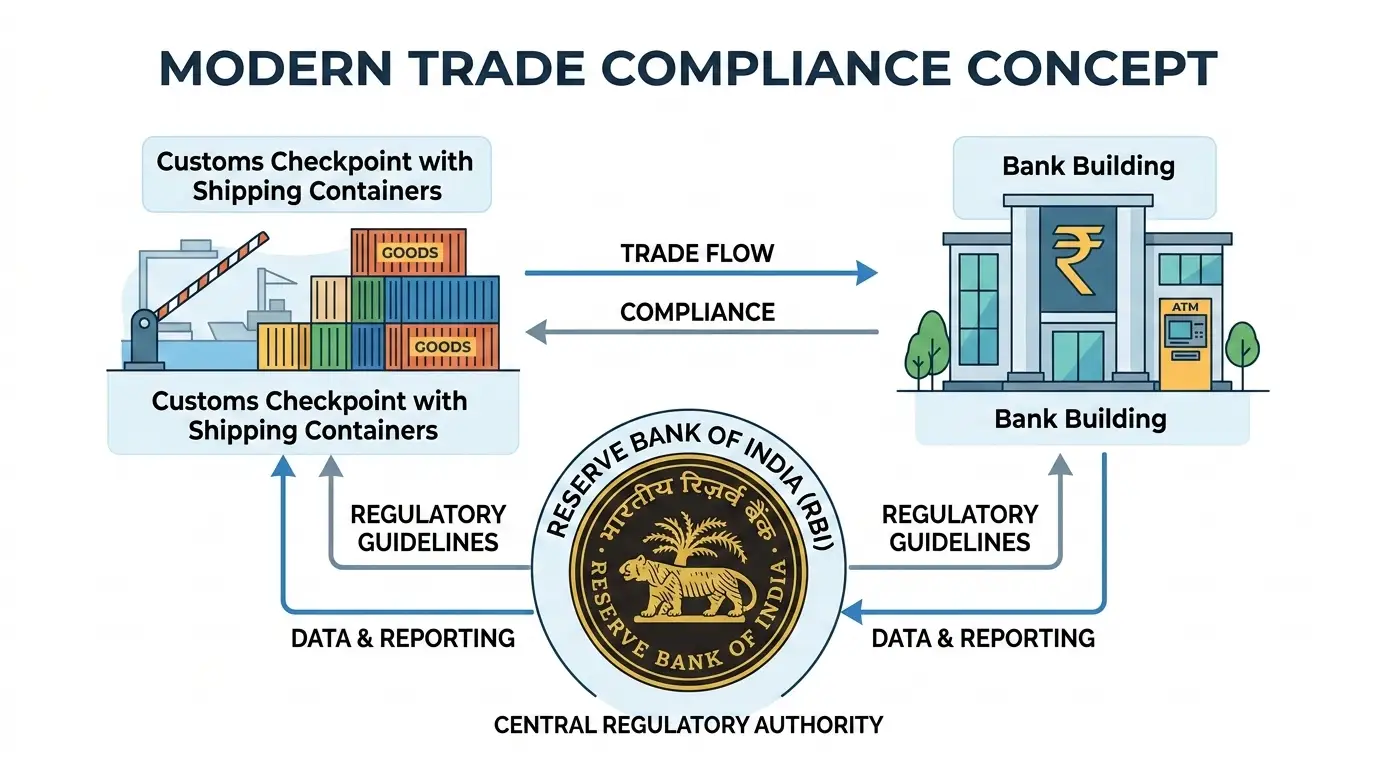
The Reserve Bank of India (RBI) runs two core trade-monitoring platforms: IDPMS for imports and EDPMS for exports. Together they connect Customs, authorised dealer (AD) banks, and RBI so that every dollar of foreign exchange going out or coming into India is matched with actual trade.
The Import Data Processing and Monitoring System (IDPMS) is RBI’s central digital platform to track import transactions from shipment to final payment. It went live nationwide on 10 October 2016 after pilot work and system changes at banks and Customs.IDPMS links Customs’ Bill of Entry (BoE) data with your AD bank’s outward remittance data so that every payment in foreign currency is backed by genuine goods entering India. On the other hand, EDPMS tracks shipping bills and realisation of export proceeds, replacing the old physical FIRC regime with electronic eBRCs.
Why IDPMS Exists
RBI’s working group recommended a robust IT system to replace fragmented, paper‑based import monitoring and to tighten control over foreign exchange outflows. The stated objective is to “facilitate efficient processing of all import transactions and effective monitoring thereof,” ensuring payments align with actual BoEs filed at Customs.In practical terms, IDPMS helps prevent:
- Over‑invoicing or fake imports to siphon money out of India.
- Long‑pending, unreconciled import payments that never get matched with BoEs.
- Gaps in FEMA reporting across different banks and ports.
How IDPMS Integrates the Ecosystem
IDPMS works on a three‑way data flow:
- Customs / ICEGATE: Generates and uploads BoE data (BoE number, date, port, value, importer IEC, AD code) to RBI’s secure server.
- RBI IDPMS server: Acts as the central hub, distributing BoE data to the relevant AD bank based on the AD code.
- AD banks: Download BoEs daily, capture outward remittance data (ORM), and match BoE–ORM pairs to close import transactions. This integration ensures that every rupee of foreign currency sent abroad via the banking system is traceable back to a specific BoE and importer under FEMA.
What Is EDPMS?
The Export Data Processing and Monitoring System (EDPMS) is RBI’s platform for tracking export shipments and the realisation of export proceeds. EDPMS has been operational since March 2014 and centralises export reporting that was earlier scattered across multiple returns and statements. Its core objective is to ensure exporters actually receive and repatriate foreign currency for goods or services shipped abroad within prescribed timelines. That realisation is what finally lets a shipping bill be closed, here's the full walkthrough of shipping bill closure in EDPMS.
From Physical FIRC to eBRC
Before EDPMS, banks issued a physical Foreign Inward Remittance Certificate (FIRC) for each export‑related remittance. In May 2016 RBI decided to discontinue issuing physical FIRCs for export payments and instead route all such data through EDPMS. Since June 20, 2016, banks issue electronic FIRCs (e‑FIRCs) and then generate electronic Bank Realisation Certificates (eBRCs) from EDPMS data. Today, eBRCs pulled from EDPMS are mandatory for GST refunds and export incentive claims with DGFT and tax authorities.
Why This Matters to Exporters
For exporters, EDPMS does the mirror job of IDPMS:
- Captures shipping bill data from Customs and other export platforms (SEZ, STPI).
- Monitors whether export proceeds are realised within the allowed period.
- Flags long-pending shipping bills, so your bank can follow up before the one-year rule in Regulation 13 limits you to advance or LC terms.
How IDPMS Works: 10‑Step Import Lifecycle
The IDPMS lifecycle for a typical goods import can be broken into ten practical steps.
Step 1: Import Shipment Initiated
The importer places a purchase order and the overseas supplier ships goods toward India under agreed Incoterms.
Step 2: Bill of Entry Filed at Customs
On arrival, the Customs House Agent (CHA) files the BoE at the port or airport via ICEGATE, with correct IEC details and a valid 14‑digit AD code of the importer’s bank.
Step 3: BoE Data Transmitted to RBI
For EDI ports, Customs automatically pushes BoE data to RBI’s IDPMS server, for non‑EDI/manual ports, the importer’s AD bank uploads BoE details using the “Manual BoE Reporting” message.
Step 4: BoE Appears in Bank’s IDPMS Queue
The BoE now shows as an “outstanding import bill” or open BoE in the AD bank’s IDPMS dashboard, waiting to be linked to payment.
Step 5: Document Submission to Bank
The importer submits BoE, commercial invoice, packing list, transport document (BL/AWB), and any other required papers to the AD bank. The bank uses these to verify that the BoE genuinely belongs to the importer and to map it correctly in IDPMS.
Step 6: Import Payment Processed
The importer remits payment (advance or post‑shipment) through the AD bank via SWIFT/wire transfer, letter of credit negotiation, or other modes permitted under the Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023. The bank processes the remittance subject to KYC and FEMA checks.
Step 7: ORM (Outward Remittance Message) Generated
For each eligible outward remittance, the AD bank creates an Outward Remittance Message (ORM) in IDPMS as mandated by RBI. The ORM is a unique digital acknowledgement of the payment.
Step 8: Payment Matching in IDPMS
The bank matches ORM entries with corresponding BoEs using the “BoE Settlement” message format. Multiple ORMs can settle a single BoE and, conversely, a single large ORM can be apportioned against multiple BoEs.
Step 9: BoE Closure
Once the bank is satisfied that payments and documents align with the BoE value (after any reduction or adjustment your bank allows), it marks the BoE as “closed” in IDPMS.
Step 10: Overdue Monitoring & Escalation
If BoEs remain unmatched or partially settled beyond the contract period, they appear as overdue or outstanding entries. Banks must follow up with the importer for documents (Regulation 18(1)(f)). Where an advance was paid and the import never happened, an entry left open means every future advance needs a standby letter of credit or a guarantee (Regulation 12(2)). Banks must also report doubtful transactions to the Directorate of Enforcement.
A simple example: A manufacturer imports raw material worth ₹50 lakh on 90‑day credit and pays in three instalments. The bank will see one BoE for ₹50 lakh, three ORMs over 90 days, and then close that BoE once all three ORMs are mapped and minor differences (FX, charges) are adjusted.
AD Code (Authorised Dealer Code)
An AD code is a 14‑digit identifier issued by your AD bank that links your current account and branch to Customs and RBI systems. You must register this code on ICEGATE for each port where you file shipping bills or BoEs, without it, Customs systems cannot route BoE data to the correct bank.
A wrong or missing AD code means your BoE may not land in your bank’s IDPMS queue at all, making payment reconciliation almost impossible until the BoE is amended or the code corrected.
How to Check IDPMS Status Online
Importers cannot log in to IDPMS directly, but there are two practical ways to track BoE status.
Option 1: ICEGATE “Status of BE in RBI‑IDPMS”
The ICEGATE portal provides a public service called “Status of BE in RBI‑IDPMS” which lets you check whether a specific BoE has been transmitted to and processed in IDPMS. You typically need:
- BoE number.
- BoE date.
Location/port code.The portal then displays BoE details and the date of transmission to RBI/IDPMS, helping you confirm that Customs data has reached your bank’s system.
Option 2: Through Your AD Bank
AD banks have full dashboard access to IDPMS and can generate reports of all outstanding, matched, and closed BoEs for each importer. Many banks now share monthly IDPMS statements or on‑demand snapshots, which are valuable for early detection of mismatches or overdue entries.
Common IDPMS Mistakes That Hurt Importers
Practical experience shows most IDPMS issues are preventable and arise from process gaps rather than fraud.
- Delayed BoE submission to bank: When importers do not share BoE copies promptly, banks cannot verify or link entries. Persistent delays bring repeated follow-up from your bank. Since 1 October 2026 a bank cannot levy a charge or penalty on you for a regulatory delay (Regulation 19(3)), but the entry stays open against your name until it is closed.
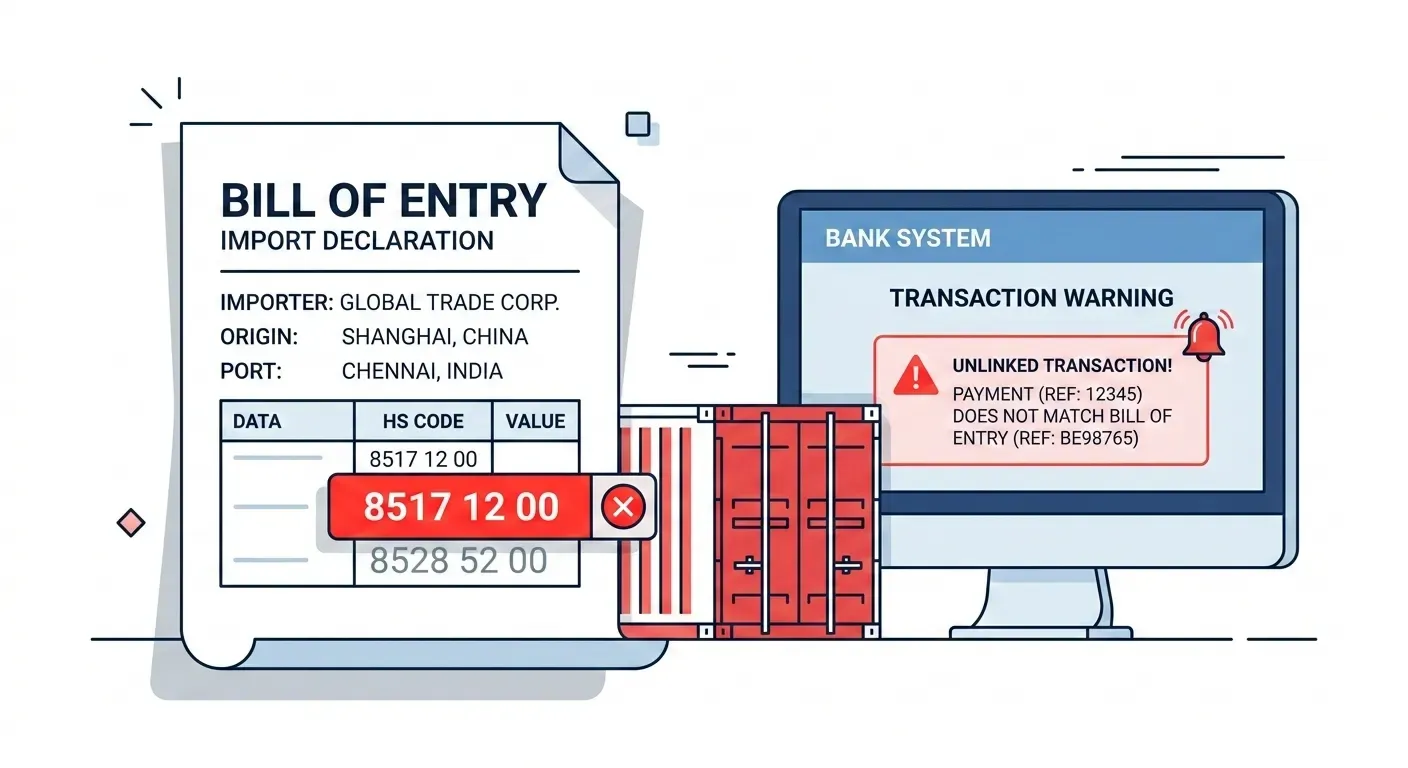
- Invoice–payment mismatch: FX fluctuations, bank charges, discounts, or freight/insurance adjustments can cause ORM amounts to differ from BoE values. If importers do not proactively explain these differences, BoEs remain open.
- Wrong or missing AD code on BoE: An incorrect AD code at the time of BoE filing routes the BoE to the wrong bank or leaves it unlinked, correction later can be time‑consuming. Until fixed, your own bank’s IDPMS will show outstanding ORMs without corresponding BoEs.
- Non‑updated shipping details or returns: If part shipments, returns, or short shipments are not communicated to the bank with supporting documents, BoE values appear inconsistent with payments.
- Ignoring overdue entries: Leaving overdue BoEs unattended is risky; banks are required to follow up on open entries and to report doubtful transactions to the Directorate of Enforcement, which in high-value matters means FEMA scrutiny.
IDPMS vs EDPMS: At‑a‑Glance
| Aspect | IDPMS (Imports) | EDPMS (Exports) |
|---|---|---|
| Direction of funds | Forex outflow from India | Forex inflow into India |
| Primary purpose | Track import payments and ensure they match BoEs | Track export shipments and ensure proceeds are realised |
| Core customs document | Bill of Entry (BoE) | Shipping Bill |
| Bank document link | ORM matched with BoE for closure | Inward remittance matched with Shipping Bill and reflected in eBRC |
| Main risk of non‑compliance | Standby LC or guarantee on future advances (Reg 12(2)), FEMA penalties, possible ED scrutiny | Advance or LC-only exports after a year past due (Reg 13), denial of incentives, FEMA penalties |
| User access | No direct importer login; accessed via AD banks and ICEGATE BoE status | No direct exporter login; status via AD banks and DGFT/eBRC systems |
FEMA 2026: What Changed on 1 October
The Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, Notification No. FEMA 23(R)/2026-RB dated 13 January 2026 and amended on 22 September 2026, came into force on 1 October 2026. RBI's Directions of 16 January 2026 (A.P. (DIR Series) Circular No. 20, RBI/2025-26/194) superseded both Master Directions on export and import and 167 circulars, including the October 2025 circular on small-value closure. Its substance now sits in the Regulations themselves.
Small-value closure on declaration (₹10 lakh)
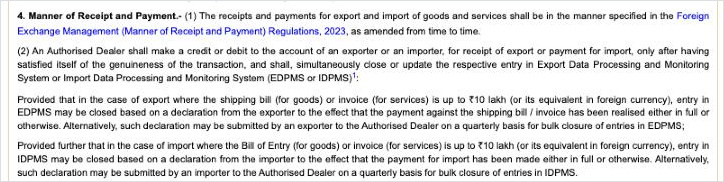
Where a shipping bill or export invoice is up to ₹10 lakh, your bank can close the EDPMS entry on your declaration that payment has been realised, in full or otherwise. The same applies in IDPMS where a Bill of Entry or import invoice is up to ₹10 lakh. Exporters and importers can submit the declaration quarterly for bulk closure (Regulation 4(2)). On the export side, a reduction in export value up to ₹10 lakh per shipping bill or invoice can also be allowed on your declaration (Regulation 6).
Services are now in both systems
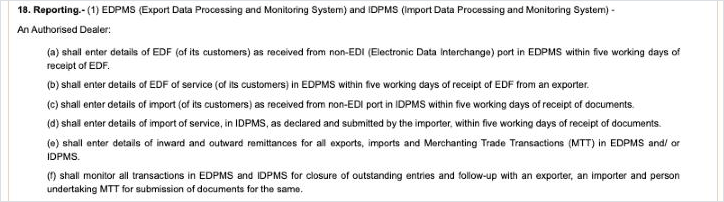
Service exporters file an Export Declaration Form (EDF), and the bank enters it in EDPMS within five working days (Regulation 18(1)(b)). Imports of services are entered in IDPMS from the documents the importer submits, also within five working days (Regulation 18(1)(d)). What this means for each side, and what your bank will ask for, is in our guide to the EDF form and IDPMS for services.
The timelines
Export proceeds must be realised within nine months from shipment for goods and from invoice for services, or twelve months where the export is invoiced or settled in Indian Rupees. Your AD bank can extend this on request (Regulation 5). Import payments are due within the period in the underlying contract, and your AD bank can extend that too (Regulation 9). Entries from non-EDI ports go in within five working days of the bank receiving the documents (Regulation 18(1)(a) and (c)).
What replaced caution listing
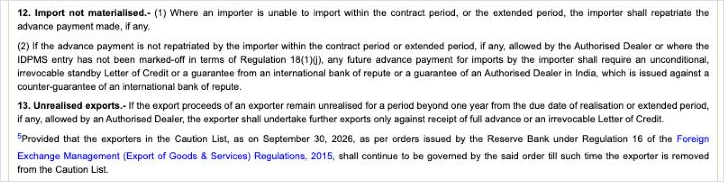
For exports, Regulation 13: if proceeds stay unrealised for more than one year beyond the due date, or any extension your bank allowed, you may export further only against full advance or an irrevocable letter of credit. Exporters already on the Caution List on 30 September 2026 stay on it until they are removed. For imports, Regulation 12(2): if an advance is not brought back when the import does not happen, or its IDPMS entry is not closed, every future advance for imports needs an unconditional, irrevocable standby letter of credit or a guarantee.
Charges and your bank's policy
Every AD bank must publish its policy and the main features of its SOP on its website (Regulation 19(4)). Its charges must be reasonable and proportional, and it cannot levy any charge or penalty on you for a regulatory delay or violation (Regulation 19(3)).
Frequently Asked Questions
Frequently Asked Questions
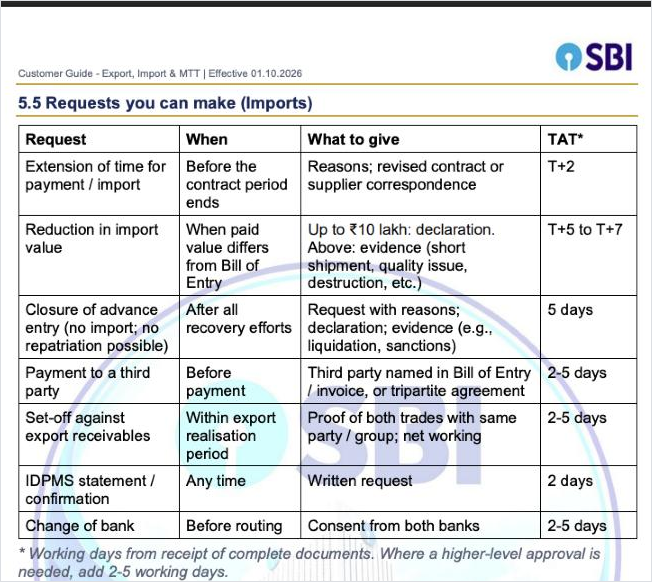
If documents and payments line up cleanly, banks can usually close an IDPMS entry within about a week of receiving complete information, though complex cases take longer. SBI's published turnaround for an IDPMS reduction or closure request, for example, is five to seven working days.
BoEs that remain unmatched beyond the contract period are flagged as overdue, and your bank must follow up for documents (Regulation 18(1)(f)). If you paid an advance and the import never happened, an entry left open means every future advance for imports needs a standby letter of credit or a guarantee (Regulation 12(2)).
Yes, if you tell both banks. Regulation 10(2) lets an importer route an advance payment and its later payments through another AD bank once it has intimated the change to both. In practice, banks coordinate through ORMs and BoE data when you inform them in advance.
Your bank can close the entry at the reduced value once it is satisfied of the reason (Regulation 18(1)(k)). Where the Bill of Entry is up to ₹10 lakh, it can be closed on your declaration alone (Regulation 4(2)). Larger reductions need supporting documents.
Yes. Since 1 October 2026, your AD bank enters imports of services in IDPMS from the documents you submit, within five working days (Regulation 18(1)(d)).