RBI Purpose Code List 2026: All 297 Codes, Inward and Outward
The complete RBI purpose code list: 138 inward P codes, 136 outward S codes, 23 cover page codes, from the current 2012 annexure, not the withdrawn one.
Listen to article
Audio version (0% complete)
Every foreign currency payment that crosses an Indian bank carries a five character purpose code. Your bank puts it on the transaction whether you choose it or not, and it is the single field that decides how RBI classifies your money in India's balance of payments.
Here is the complete current list. All 297 codes, both directions, in RBI's own wording.
TL;DR
- There are 297 codes: 138 inward (P), 136 outward (S), and 23 cover page codes that only banks use for fortnightly aggregates.
- P means money into India, S means money out. The letter describes the bank's side of the trade, not yours, so an exporter being paid uses a P code.
- The annexure most sites quote has been withdrawn since 2012. RBI PDFs 52220 and 52221 are stamped Withdrawn. The current list is Annex I to A.P. (DIR Series) Circular No. 84 dated 29 February 2012, effective 1 April 2012.
- Three things changed in that revision and are still published wrong elsewhere. Group 04, Communication Services, was abolished, so S0401 to S0404 no longer exist. Merchanting became a goods flow, S0108 and P0108, not S1001 and P1001. Reinsurance folded into S0603.
- The codes most Indian businesses need: S0101 advance payment for imports, S0102 settling an import invoice, P0802 software consultancy, P0807 off-site software exports, P1401 salary from a foreign employer, S0023 for LRS.
- One trap. In group 10 the P and S numbers stop mirroring each other. Commission agent services is P1019 inbound but S1020 outbound, and three more behave the same way.
Search the full list here, then read on for what the codes mean and how to pick between the ones that look similar.
What a purpose code actually is
A purpose code tells RBI why foreign exchange moved. It is not a tax field, it is not a customs field, and it does not by itself decide whether your receipt is taxable. It is a statistical classification that feeds India's balance of payments, compiled under the IMF's Balance of Payments and International Investment Position Manual.
That statistical origin explains most of what feels strange about the list. Codes are grouped the way an economist groups trade flows, not the way a business thinks about its own invoices. There is a code for museums and archival services and no single obvious code for "I am a freelancer and somebody in Texas paid me". The list was never designed around your use case.
It matters anyway, for three practical reasons. Your bank cannot release the funds without one. The code drives which documents the bank asks you for, because an export receipt needs different paperwork from a gift. And the code sits on your FIRA, which is the document your CA and any future auditor will read.
How to read the code
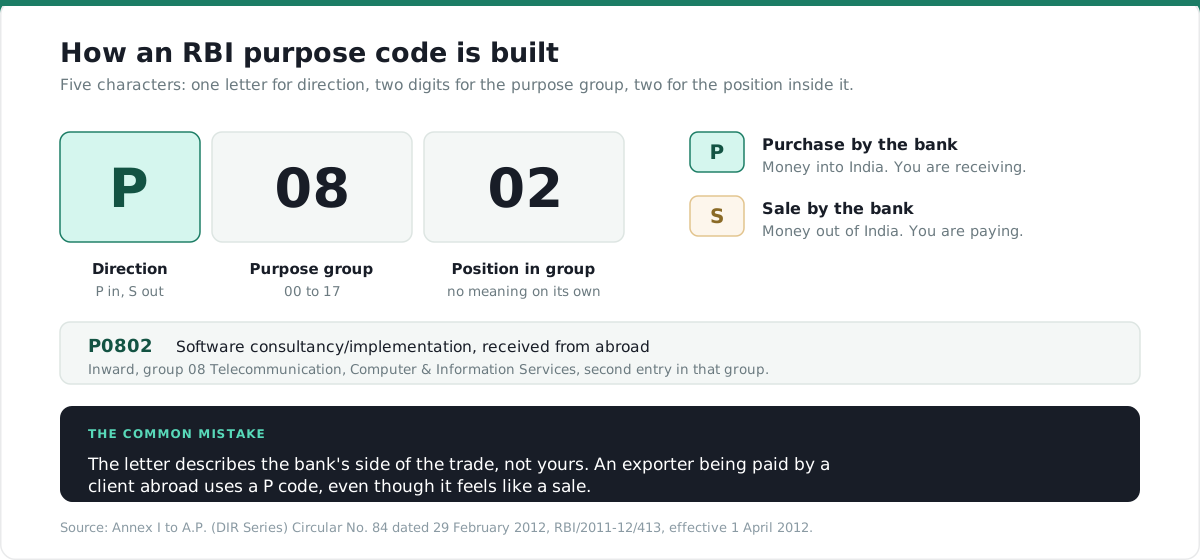
Every code is five characters: one letter and four digits.
The letter is the direction, from the bank's point of view, not yours.
- P means a purchase of foreign exchange by the bank, which is money coming into India. Inward remittance. You are receiving.
- S means a sale of foreign exchange by the bank, which is money leaving India. Outward remittance. You are paying.
This trips people up constantly. If you are an exporter being paid by a US client, you want a P code, even though from where you sit it feels like a sale.
The first two digits are the purpose group. 00 is capital account, 01 is goods, 02 is transport, 08 is technology and telecom, 10 is other business services, and so on up to 17.
The last two digits are the serial position inside that group. They carry no independent meaning, and, as you will see further down, they do not reliably match between the P and S lists.
The source problem: which annexure is current
This is worth three paragraphs because it is the reason so many purpose code pages are wrong.
Search for the RBI purpose code list and you will be pointed at two PDFs on the RBI site, numbered 52220 and 52221. Large, credible sites link to them. Both are stamped Withdrawn on every page.
They are not merely re-filed. They are genuinely out of date, and you can prove it from the contents rather than the stamp. Neither file contains S0807, the code for off-site software imports. Neither contains S1014 through S1023, which cover engineering, tax consulting, market research, publishing, mining and commission agent services. Neither contains S1601 or S1701, or the whole S1408 to S1412 block that banks use for FDI dividends and profit. Those codes are in use every day.
The current list is Annex I to A.P. (DIR Series) Circular No. 84 dated February 29, 2012, reference RBI/2011-12/413, titled "Compilation of R-Returns: Reporting under FETERS". It took effect for transactions performed on and after 1 April 2012, and it is still cited as a source circular in RBI's current Master Direction on Export of Goods and Services. That circular is the source for everything below.
One thing it is not: the Master Direction on Reporting under FEMA. That document, updated 24 June 2026, contains the reporting forms and returns but no purpose codes at all. If somebody sends you there, they have not opened it.
What the 2012 revision changed
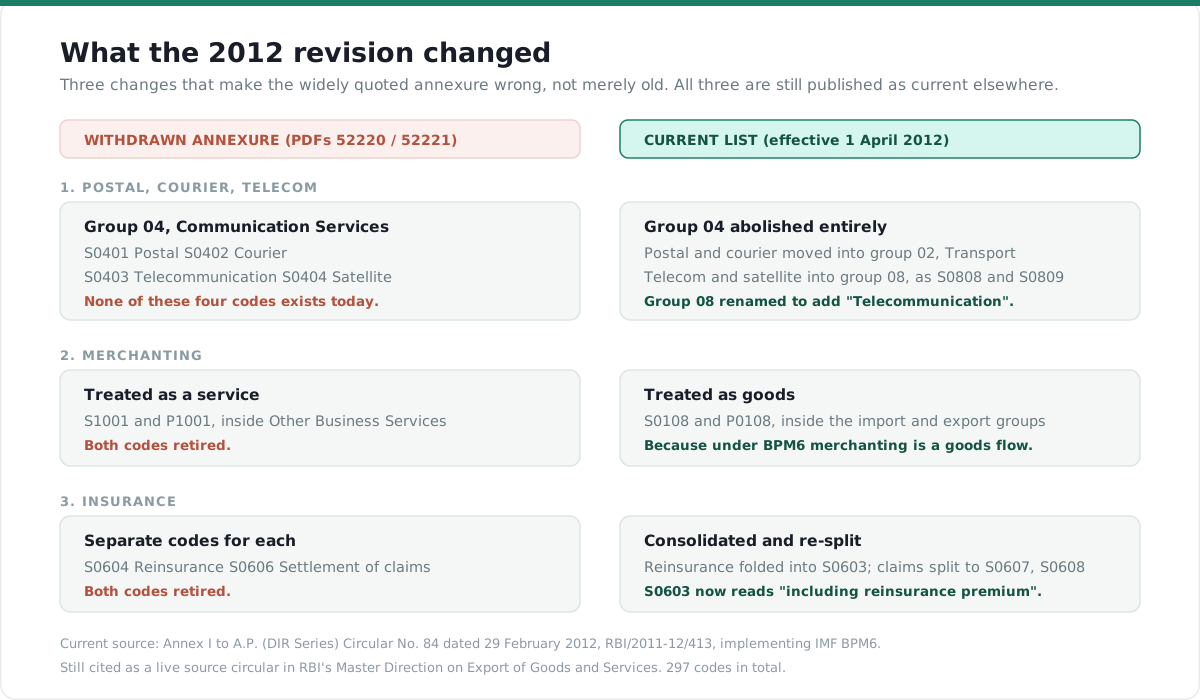
The revision moved Indian reporting from the IMF's fifth edition manual to its sixth. Three changes matter if you are reading an older list.
Group 04, Communication Services, was abolished. S0401 postal, S0402 courier, S0403 telecommunication and S0404 satellite no longer exist. Postal and courier moved into group 02, Transport. Telecommunication and satellite moved into group 08, which was renamed from "Computer & Information Services" to "Telecommunication, Computer & Information Services" and gained S0808 and S0809. Several major published lists still show the old four as current.
Merchanting moved from services into goods. Under the sixth edition manual, buying from one non-resident and selling to another without the goods entering India is a goods transaction, not a service. So S1001 became S0108 and P1001 became P0108, both sitting in the goods groups.
Insurance codes were consolidated. S0604 and S0606 are gone. Reinsurance folded into S0603, whose description now reads "Other general insurance premium including reinsurance premium; and term life insurance premium". Claim settlement split into S0607 and S0608.
Two smaller ones worth knowing: the old combined stevedoring code S0213 split into S0214 for shipping and S0215 for airlines, and the old catch-all S1019 was replaced by S1099 so that S1020 to S1023 could take over the vacated numbers.
Complete list: inward remittance, P codes
138 codes. Use these when money is coming into India. Descriptions are RBI's own, reproduced without editing, including the places where RBI's punctuation and spacing are untidy.
Group 00, Capital Account
| Code | Description |
|---|---|
| P0017 | Receipts on account of Sale of non-produced non-financial assets (Sale of intangible assets like patents, copyrights, trademarks etc., land acquired by government, use of natural resources) – Government |
| P0019 | Receipts on account of Sale of non-produced non-financial assets (Sale of intangible assets like patents, copyrights, trademarks etc., use of natural resources) – Non-Government |
| P0028 | Capital transfer receipts (Guarantee payments, Investment Grant given by the government/international organisation, exceptionally large Non-life insurance claims including claims arising out of natural calamity) - Government |
| P0029 | Capital transfer receipts ( Guarantee payments, Investment Grant given by the Non-government, exceptionally large Non-life insurance claims including claims arising out of natural calamity) – Non-Government |
| P0099 | Other capital receipts not included elsewhere |
Group 00, Financial Account
Foreign Direct Investment
| Code | Description |
|---|---|
| P0003 | Repatriation of Indian Direct investment abroad (by branches & wholly owned subsidiaries and associates) in equity shares |
| P0004 | Repatriation Indian Direct investment abroad (by branches & wholly owned subsidiaries and associates) in debt instruments |
| P0005 | Repatriation of Indian investment abroad in real estate |
| P0006 | Foreign Direct Investment made by overseas Investors in India in equity shares |
| P0007 | Foreign Direct Investment made by overseas Investors in India in debt instruments. |
| P0008 | Foreign Direct Investment made by overseas Investors in India in real estate |
Foreign Portfolio Investment
| Code | Description |
|---|---|
| P0001 | Repatriation of Indian Portfolio investment abroad in equity capital (shares) |
| P0002 | Repatriation of Indian Portfolio investment abroad in debt instruments. |
| P0009 | Foreign Portfolio Investment made by overseas Investors in India in equity shares |
| P0010 | Foreign Portfolio Investment made by overseas Investors in India in debt Instruments. |
External Commercial Borrowings
| Code | Description |
|---|---|
| P0011 | Repayment of loans extended to Non-Residents |
| P0012 | Long & medium term loans, with original maturity of above one year, from Non-Residents to India (External Commercial Borrowings) |
Short term credits
| Code | Description |
|---|---|
| P0013 | Short term loans with original maturity upto one year from Non-Residents to India (Short-term Trade Credit) |
Banking Capital
| Code | Description |
|---|---|
| P0014 | Receipts o/a Non-Resident deposits (FCNR(B)/NR(E)RA, etc.) {ADs should report these even if funds are not "swapped" into Rupees} |
| P0015 | Loans & overdrafts taken by ADs on their own account. (Any amount of loan credited to the NOSTRO account which may not be swapped into Rupees should also be reported) |
| P0016 | Purchase of a foreign currency against another currency. |
Financial Derivatives and Others
| Code | Description |
|---|---|
| P0020 | Receipts on account of margin payments, premium payment and settlement amount etc. under Financial derivative transactions |
| P0021 | Receipts on account of sale of share under Employee stock option |
| P0022 | Receipts on account of other investment in ADRs/GDRs |
External Assistance
| Code | Description |
|---|---|
| P0024 | External Assistance received by India e.g. Multilateral and bilateral loans received by Govt. of India under agreements with other govt. / international institutions. |
| P0025 | Repayments received on account of External Assistance extended by India |
Group 01, Exports of Goods
| Code | Description |
|---|---|
| P0101 | Value of export bills negotiated / purchased/discounted etc. (covered under GR/PP/SOFTEX/EC copy of shipping bills etc.) – Other than Nepal and Bhutan |
| P0102 | Realisation of export bills (in respect of goods) sent on collection (full invoice value) – Other than Nepal and Bhutan |
| P0103 | Advance receipts against export contracts, which will be covered later by GR/PP/SOFTEX/SDF – other than Nepal and Bhutan |
| P0104 | Receipts against export of goods not covered by the GR /PP /SOFTEX /EC copy of shipping bill etc. (under Intermediary/transit trade, i.e., third country export passing through India |
| P0105 | Export bills (in respect of goods) sent on collection – other than Nepal and Bhutan |
| P0107 | Realisation of NPD export bills (full value of bill to be reported) – other than Nepal and Bhutan |
| P0108 | Goods sold under merchanting / Receipt against export leg of merchanting trade* |
| P0109 | Export realisation on account of exports to Nepal and Bhutan, if any |
Two things here catch people out. P0106 no longer exists; the old code for converting overdue export bills was dropped. And Nepal and Bhutan are carved out. P0101 through P0105 all say "other than Nepal and Bhutan", and receipts from those two countries go to P0109 instead.
The asterisk on P0108 is RBI's own footnote: "'Merchanting' here refers to purchase/sale of goods from/to a non-resident combined with subsequent resale of the same goods to another non-resident without goods being present in the compiling economy (resident's economy). Essentially, goods transaction would be termed as 'merchanting' if goods acquired do not enter the territory of the compiling (resident's) economy and secondly, goods being acquired do not undergo any transformation before being resold or repurchased".
Group 02, Transport
| Code | Description |
|---|---|
| P0201 | Receipts of surplus freight/passenger fare by Indian shipping companies operating abroad |
| P0202 | Receipts on account of operating expenses of Foreign shipping companies operating in India |
| P0205 | Receipts on account of operational leasing (with crew) – Shipping companies |
| P0207 | Receipts of surplus freight/passenger fare by Indian Airlines companies operating abroad. |
| P0208 | Receipt on account of operating expenses of Foreign Airlines companies operating in India |
| P0211 | Receipt on account of operational leasing (with crew) – Airlines companies |
| P0214 | Receipts on account of other transportation services (stevedoring, demurrage, port handling charges etc).(Shipping Companies) |
| P0215 | Receipts on account of other transportation services (stevedoring, demurrage, port handling charges etc).( Airlines companies) |
| P0216 | Receipts of freight fare -Shipping companies operating abroad |
| P0217 | Receipts of passenger fare by Indian Shipping companies operating abroad |
| P0218 | Other receipts by Shipping companies |
| P0219 | Receipts of freight fare by Indian Airlines companies operating abroad |
| P0220 | Receipts of passenger fare –Airlines |
| P0221 | Other receipts by Airlines companies |
| P0222 | Receipts on account of freights under other modes of transport (Internal Waterways, Roadways, Railways, Pipeline transports and Others) |
| P0223 | Receipts on account of passenger fare under other modes of transport (Internal Waterways, Roadways, Railways, Pipeline transports and Others) |
| P0224 | Postal & Courier services by Air |
| P0225 | Postal & Courier services by Sea |
| P0226 | Postal & Courier services by others |
Group 03, Travel
| Code | Description |
|---|---|
| P0301 | Purchases towards travel (Includes purchases of foreign TCs, currency notes etc over the counter, by hotels, Emporiums, institutions etc. as well as amount received by TT/SWIFT transfers or debit to Non-Resident account). |
| P0302 | Business travel |
| P0304 | Travel for medical treatment including TCs purchased by hospitals |
| P0305 | Travel for education including TCs purchased by educational institutions |
| P0306 | Other travel receipts |
| P0308 | Foreign Currencies/TCs surrendered by returning Indian tourists. |
There is no P0303. Pilgrimage exists as an outward code, S0303, but not as an inward one.
Group 05, Construction Services
| Code | Description |
|---|---|
| P0501 | Receipts on account of services relating to cost of construction of projects in India |
| P0502 | Receipts on account of construction works carried out abroad by Indian Companies |
Group 06, Insurance and Pension Services
| Code | Description |
|---|---|
| P0601 | Life Insurance premium except term insurance |
| P0602 | Freight insurance – relating to import & export of goods |
| P0603 | Other general insurance premium including reinsurance premium; and term life insurance premium |
| P0605 | Auxiliary services including commission on insurance |
| P0607 | Insurance claim Settlement of non-life insurance; and life insurance (only term insurance) |
| P0608 | Life insurance claim settlements (excluding term insurance) received by residents in India |
| P0609 | Standardised guarantee services |
| P0610 | Premium for pension funds |
| P0611 | Periodic pension entitlements e.g. monthly quarterly or yearly payments of pension amounts by Indian Pension Fund Companies. |
| P0612 | Invoking of standardised guarantees |
Group 07, Financial Services
| Code | Description |
|---|---|
| P0701 | Financial intermediation except investment banking – Bank charges, collection charges, LC charges, etc. |
| P0702 | Investment banking – brokerage, under writing commission etc. |
| P0703 | Auxiliary services – charges on operation & regulatory fees, custodial services, depository services etc. |
Group 08, Telecommunication, Computer & Information Services
| Code | Description |
|---|---|
| P0801 | Hardware consultancy/implementation |
| P0802 | Software consultancy/implementation (other than those covered in SOFTEX form) |
| P0803 | Data base, data processing charges |
| P0804 | Repair and maintenance of computer and software |
| P0805 | News agency services |
| P0806 | Other information services- Subscription to newspapers, periodicals, etc. |
| P0807 | Off-site Software Exports |
| P0808 | Telecommunication services including electronic mail services and voice mail services |
| P0809 | Satellite services including space shuttle and rockets, etc. |
This is the group most Indian software and services exporters land in. The distinction that matters is P0802 versus P0807. P0802 is consultancy and implementation, explicitly "other than those covered in SOFTEX form". P0807 is off-site software exports. If your contract is a SOFTEX filing, you are not in P0802.
Group 09, Charges for the use of intellectual property n.i.e
| Code | Description |
|---|---|
| P0901 | Franchises services |
| P0902 | Receipts for use, through licensing arrangements, of produced originals or prototypes (such as manuscripts and films), patents, copyrights, trademarks, industrial processes, franchises etc. |
Group 10, Other Business Services
| Code | Description |
|---|---|
| P1002 | Trade related services – commission on exports / imports |
| P1003 | Operational leasing services (other than financial leasing) without operating crew, including charter hire- Airlines companies |
| P1004 | Legal services |
| P1005 | Accounting, auditing, book keeping services |
| P1006 | Business and management consultancy and public relations services |
| P1007 | Advertising, trade fair service |
| P1008 | Research & Development services |
| P1009 | Architectural services |
| P1010 | Agricultural services like protection against insects & disease, increasing of harvest yields, forestry services. |
| P1011 | Inward remittance for maintenance of offices in India |
| P1013 | Environmental Services |
| P1014 | Engineering Services |
| P1015 | Tax consulting services |
| P1016 | Market research and public opinion polling service |
| P1017 | Publishing and printing services |
| P1018 | Mining services like on–site processing services analysis of ores etc. |
| P1019 | Commission agent services |
| P1020 | Wholesale and retailing trade services. |
| P1021 | Operational leasing services (other than financial leasing) without operating crew, including charter hire- Shipping companies |
| P1022 | Other Technical Services including scientific/space services. |
| P1099 | Other services not included elsewhere |
Group 11, Personal, Cultural & Recreational services
| Code | Description |
|---|---|
| P1101 | Audio-visual and related services like Motion picture and video tape production, distribution and projection services. |
| P1103 | Radio and television production, distribution and transmission services |
| P1104 | Entertainment services |
| P1105 | Museums, library and archival services |
| P1106 | Recreation and sporting activity services |
| P1107 | Educational services (e.g. fees received for correspondence courses offered to non-resident by Indian institutions) |
| P1108 | Health Service (Receipts on account of services provided by Indian hospitals, doctors, nurses, paramedical and similar services etc. rendered remotely or on-site) |
| P1109 | Other Personal, Cultural & Recreational services |
Group 12, Government not included elsewhere
| Code | Description |
|---|---|
| P1201 | Maintenance of foreign embassies in India |
| P1203 | Maintenance of international institutions such as offices of IMF mission, World Bank, UNICEF etc. in India. |
Group 13, Secondary Income
| Code | Description |
|---|---|
| P1301 | Inward remittance from Indian non-residents towards family maintenance and savings |
| P1302 | Personal gifts and donations |
| P1303 | Donations to religious and charitable institutions in India |
| P1304 | Grants and donations to governments and charitable institutions established by the governments |
| P1306 | Receipts / Refund of taxes |
| P1307 | Receipts on account of migrant transfers including Personal Effects |
Group 14, Primary Income
| Code | Description |
|---|---|
| P1401 | Compensation of employees |
| P1403 | Inward remittance towards interest on loans extended to non-residents (ST/MT/LT loans) |
| P1405 | Inward remittance towards interest receipts of ADs on their own account (on investments.) |
| P1408 | Inward remittance of profit by branches of Indian FDI Enterprises (including bank branches) operating abroad. |
| P1409 | Inward remittance of dividends (on equity and investment fund shares) by Indian FDI Enterprises, other than branches, operating abroad |
| P1410 | Inward remittance on account of interest payment by Indian FDI enterprises operating abroad to their Parent company in India. |
| P1411 | Inward remittance of interest income on account of Portfolio Investment made abroad by India |
| P1412 | Inward remittance of dividends on account of Portfolio Investment made abroad by India on equity and investment fund shares |
| P1499 | Other income receipts |
P1401, compensation of employees, is the code for salary. If you are resident in India and employed by a company abroad, your salary arrives under P1401, not under any of the services codes. This is one of the most commonly miscoded receipts in the whole list, because the money often looks like a consulting fee to whoever is tagging it.
Group 15, Others
| Code | Description |
|---|---|
| P1501 | Refunds / rebates on account of imports |
| P1502 | Reversal of wrong entries, refunds of amount remitted for non-imports |
| P1503 | Remittances (receipts) by residents under international bidding process. |
| P1505 | Deemed Exports ( exports between SEZ, EPZs and Domestic Tariff Areas) |
Group 16, Maintenance and repair services n.i.e
| Code | Description |
|---|---|
| P1601 | Receipts on account of maintenance and repair services rendered for Vessels, Ships, Boats, Warships, etc. |
| P1602 | Receipts of maintenance and repair services rendered for aircrafts, Space shuttles, Rockets, military aircrafts, etc. |
Group 17, Manufacturing services
| Code | Description |
|---|---|
| P1701 | Receipts on account of processing of goods |
Complete list: outward remittance, S codes
136 codes. Use these when money is leaving India.
Group 00, Capital Account
| Code | Description |
|---|---|
| S0017 | Acquisition of non-produced non-financial assets (Purchase of intangible assets like patents, copyrights, trademarks etc., land acquired by government, use of natural resources) – Government |
| S0019 | Acquisition of non-produced non-financial assets (Purchase of intangible assets like patents, copyrights, trademarks etc., use of natural resources) – Non-Government |
| S0026 | Capital transfers ( Guarantees payments, Investment Grand given by the government/international organisation, exceptionally large Non-life insurance claims) – Government |
| S0027 | Capital transfers ( Guarantees payments, Investment Grand given by the Non-government, exceptionally large Non-life insurance claims) – Non-Government |
| S0099 | Other capital payments not included elsewhere |
"Investment Grand" is RBI's own typo for "Grant" and it is reproduced here as printed, because banks match against the official wording.
Group 00, Financial Account
Foreign Direct Investments
| Code | Description |
|---|---|
| S0003 | Indian Direct investment abroad (in branches & wholly owned subsidiaries) in equity Shares |
| S0004 | Indian Direct investment abroad (in subsidiaries and associates)in debt instruments |
| S0005 | Indian investment abroad – in real estate |
| S0006 | Repatriation of Foreign Direct Investment made by overseas Investors in India – in equity shares |
| S0007 | Repatriation of Foreign Direct Investment in made by overseas Investors India – in debt instruments |
| S0008 | Repatriation of Foreign Direct Investment made by overseas Investors in India – in real estate |
Foreign Portfolio Investments
| Code | Description |
|---|---|
| S0001 | Indian Portfolio investment abroad – in equity shares |
| S0002 | Indian Portfolio investment abroad – in debt instruments |
| S0009 | Repatriation of Foreign Portfolio Investment made by overseas Investors in India – in equity shares |
| S0010 | Repatriation of Foreign Portfolio Investment made by overseas Investors in India – in debt instruments |
External Commercial Borrowings
| Code | Description |
|---|---|
| S0011 | Loans extended to Non-Residents |
| S0012 | Repayment of long & medium term loans with original maturity above one year received from Non-Residents |
Short term Loans
| Code | Description |
|---|---|
| S0013 | Repayment of short term loans with original maturity up to one year received from Non-Residents |
Banking Capital
| Code | Description |
|---|---|
| S0014 | Repatriation of Non-Resident Deposits (FCNR(B)/NR(E)RA etc) |
| S0015 | Repayment of loans & overdrafts taken by ADs on their own account. |
| S0016 | Sale of a foreign currency against another foreign currency |
Financial Derivatives and Others
| Code | Description |
|---|---|
| S0020 | Payments made on account of margin payments, premium payment and settlement amount etc. under Financial derivative transactions. |
| S0021 | Payments made on account of sale of share under Employee stock option |
| S0022 | Investment in Indian Depositories Receipts (IDRs) |
| S0023 | Remittances made under Liberalised Remittance Scheme (LRS) for Individuals |
S0023 is the LRS code. It has no inward twin, because LRS is an outbound scheme only.
External Assistance
| Code | Description |
|---|---|
| S0024 | External Assistance extended by India.e.g.Loans and advances extended by India to Foreign governments under various agreements |
| S0025 | Repayments made on account of External Assistance received by India. |
Group 01, Imports
| Code | Description |
|---|---|
| S0101 | Advance payment against imports made to countries other than Nepal and Bhutan |
| S0102 | Payment towards imports- settlement of invoice other than Nepal and Bhutan |
| S0103 | Imports by diplomatic missions other than Nepal and Bhutan |
| S0104 | Intermediary trade/transit trade,i.e.,third country export passing through India |
| S0108 | Goods acquired under merchanting / Payment against import leg of merchanting trade* |
| S0109 | Payments made for Imports from Nepal and Bhutan, if any |
The asterisk on S0108 is RBI's own footnote, the same one that applies to P0108: "'Merchanting' here refers to purchase/sale of goods from/to a non-resident combined with subsequent resale of the same goods to another non-resident without goods being present in the compiling economy (resident's economy)."
S0101 versus S0102 is the single most used decision on this page. S0101 is an advance, paid before the goods arrive. S0102 settles an invoice for goods already received. Getting this wrong is the most common reason an import remittance gets queried, because the bank's document expectations differ: an advance payment brings advance remittance conditions and a Bill of Entry follow-up obligation with it.
Group 02, Transport
| Code | Description |
|---|---|
| S0201 | Payments for surplus freight/passenger fare by foreign shipping companies operating in India |
| S0202 | Payment for operating expenses of Indian shipping companies operating abroad |
| S0203 | Freight on imports – Shipping companies |
| S0204 | Freight on exports – Shipping companies |
| S0205 | Operational leasing/Rental of Vessels (with crew) –Shipping companies |
| S0206 | Booking of passages abroad – Shipping companies |
| S0207 | Payments for surplus freight/passenger fare by foreign Airlines companies operating in India |
| S0208 | Operating expenses of Indian Airlines companies operating abroad |
| S0209 | Freight on imports – Airlines companies |
| S0210 | Freight on exports – Airlines companies |
| S0211 | Operational leasing / Rental of Vessels (with crew) – Airline companies |
| S0212 | Booking of passages abroad – Airlines companies |
| S0214 | Payments on account of stevedoring, demurrage, port handling charges etc.(Shipping companies) |
| S0215 | Payments on account of stevedoring, demurrage, port handling charges, etc.(Airlines companies) |
| S0216 | Payments for Passenger - Shipping companies |
| S0217 | Other payments by Shipping companies |
| S0218 | Payments for Passenger - Airlines companies |
| S0219 | Other Payments by Airlines companies |
| S0220 | Payments on account of freight under other modes of transport (Internal Waterways, Roadways, Railways, Pipeline transports and others) |
| S0221 | Payments on account of passenger fare under other modes of transport (Internal Waterways, Roadways, Railways, Pipeline transports and others) |
| S0223 | Postal & Courier services by Sea |
S0213 does not exist. It was split into S0214 and S0215 in the 2012 revision.
Group 03, Travel
| Code | Description |
|---|---|
| S0301 | Business travel. |
| S0303 | Travel for pilgrimage |
| S0304 | Travel for medical treatment |
| S0305 | Travel for education (including fees, hostel expenses etc.) |
| S0306 | Other travel (including holiday trips and payments for settling international credit cards transactions) |
S0302, the old Basic Travel Quota code, is not in the current list. Leisure travel goes to S0306, which also absorbs international credit card settlements.
Group 05, Construction Services
| Code | Description |
|---|---|
| S0501 | Construction of projects abroad by Indian companies including import of goods at project site abroad |
| S0502 | cost of construction etc. of projects executed by foreign companies in India. |
Group 06, Insurance and Pension Services
| Code | Description |
|---|---|
| S0601 | Life Insurance premium except term insurance |
| S0602 | Freight insurance – relating to import & export of goods |
| S0603 | Other general insurance premium including reinsurance premium; and term life insurance premium |
| S0605 | Auxiliary services including commission on insurance |
| S0607 | Insurance claim Settlement of non-life insurance; and life insurance (only term insurance) |
| S0608 | Life Insurance Claim Settlements |
| S0609 | Standardised guarantee services |
| S0610 | Premium for pension funds |
| S0611 | Periodic pension entitlements e.g. monthly quarterly or yearly payments of pension amounts by Indian Pension Fund Companies. |
| S0612 | Invoking of standardised guarantees |
S0604 and S0606 no longer exist.
Group 07, Financial Services
| Code | Description |
|---|---|
| S0701 | Financial intermediation, except investment banking - Bank charges, collection charges, LC charges etc. |
| S0702 | Investment banking – brokerage, under writing commission etc. |
| S0703 | Auxiliary services – charges on operation & regulatory fees, custodial services, depository services etc. |
Group 08, Telecommunication, Computer & Information Services
| Code | Description |
|---|---|
| S0801 | Hardware consultancy/implementation |
| S0802 | Software consultancy / implementation |
| S0803 | Data base, data processing charges |
| S0804 | Repair and maintenance of computer and software |
| S0805 | News agency services |
| S0806 | Other information services- Subscription to newspapers, periodicals |
| S0807 | Off-site software imports |
| S0808 | Telecommunication services including electronic mail services and voice mail services |
| S0809 | Satellite services including space shuttle and rockets etc. |
S0807 is the code for buying software from abroad, and it is the one most often missed because it did not exist in the withdrawn annexure. If you are paying an overseas SaaS vendor for software delivered electronically, this group is where you belong, not group 10.
Group 09, Charges for the use of intellectual property n.i.e
| Code | Description |
|---|---|
| S0901 | Franchises services |
| S0902 | Payment for use, through licensing arrangements, of produced originals or prototypes (such as manuscripts and films), patents, copyrights, trademarks and industrial processes etc. |
Group 10, Other Business Services
| Code | Description |
|---|---|
| S1002 | Trade related services – commission on exports / imports |
| S1003 | Operational leasing services (other than financial leasing) without operating crew, including charter hire- Airlines companies |
| S1004 | Legal services |
| S1005 | Accounting, auditing, book-keeping services |
| S1006 | Business and management consultancy and public relations services |
| S1007 | Advertising, trade fair service |
| S1008 | Research & Development services |
| S1009 | Architectural services |
| S1010 | Agricultural services like protection against insects & disease, increasing of harvest yields, forestry services. |
| S1011 | Payments for maintenance of offices abroad |
| S1013 | Environmental Services |
| S1014 | Engineering Services |
| S1015 | Tax consulting services |
| S1016 | Market research and public opinion polling service |
| S1017 | Publishing and printing services |
| S1018 | Mining services like on–site processing services analysis of ores etc. |
| S1020 | Commission agent services |
| S1021 | Wholesale and retailing trade services. |
| S1022 | Operational leasing services (other than financial leasing) without operating crew, including charter hire- Shipping companies |
| S1023 | Other Technical Services including scientific/space services. |
| S1099 | Other services not included elsewhere |
S1001 moved to S0108. S1012 and S1019 do not exist.
Group 11, Personal, Cultural & Recreational services
| Code | Description |
|---|---|
| S1101 | Audio-visual and related services like Motion picture and video tape production, distribution and projection services. |
| S1103 | Radio and television production, distribution and transmission services |
| S1107 | Education (e.g. fees for correspondence courses abroad ) |
| S1108 | Health Service (payment towards services received from hospitals, doctors, nurses, paramedical and similar services etc. rendered remotely or on-site) |
| S1109 | Other Personal, Cultural & Recreational services |
The outward list has no S1102, S1104, S1105 or S1106, even though the inward list has P1104, P1105 and P1106.
Group 12, Government not included elsewhere
| Code | Description |
|---|---|
| S1201 | Maintenance of Indian embassies abroad |
| S1202 | Remittances by foreign embassies in India |
Group 13, Secondary Income
| Code | Description |
|---|---|
| S1301 | Remittance for family maintenance and savings |
| S1302 | Remittance towards personal gifts and donations |
| S1303 | Remittance towards donations to religious and charitable institutions abroad |
| S1304 | Remittance towards grants and donations to other governments and charitable institutions established by the governments. |
| S1305 | Contributions/donations by the Government to international institutions |
| S1306 | Remittance towards payment / refund of taxes. |
Group 14, Primary Income
| Code | Description |
|---|---|
| S1401 | Compensation of employees |
| S1402 | Remittance towards interest on Non-Resident deposits (FCNR(B)/NR(E)RA, etc.) |
| S1403 | Remittance towards interest on loans from Non-Residents (ST/MT/LT loans) e.g. External Commercial Borrowings, Trade Credits, etc. |
| S1405 | Remittance towards interest payment by ADs on their own account (to VOSTRO a/c holders or the OD on NOSTRO a/c.) |
| S1408 | Remittance of profit by FDI enterprises in India (by branches of foreign companies including bank branches) |
| S1409 | Remittance of dividends by FDI enterprises in India (other than branches) on equity and investment fund shares |
| S1410 | Payment of interest by FDI enterprises in India to their Parent company abroad. |
| S1411 | Remittance of interest income on account of Portfolio Investment in India |
| S1412 | Remittance of dividends on account of Portfolio Investment in India on equity and investment fund shares |
S1404, S1406 and S1407 were replaced by the more granular S1408 to S1412 block. A page that still tells you to use S1406 for repatriation of profits is reading the withdrawn list.
Group 15, Others
| Code | Description |
|---|---|
| S1501 | Refunds / rebates / reduction in invoice value on account of exports |
| S1502 | Reversal of wrong entries, refunds of amount remitted for non-exports |
| S1503 | Payments by residents for international bidding |
| S1504 | Notional sales when export bills negotiated/ purchased/ discounted are dishonored/ crystallised/ cancelled and reversed from suspense account |
| S1505 | Deemed Imports (exports between SEZ, EPZs and Domestic tariff areas) |
Group 16, Maintenance and repair services n.i.e
| Code | Description |
|---|---|
| S1601 | Payments on account of maintenance and repair services rendered for Vessels, ships, boats, warships, etc. |
| S1602 | Payments on account of maintenance and repair services rendered for aircrafts, space shuttles, rockets, military aircrafts, helicopters, etc. |
Group 17, Manufacturing services
| Code | Description |
|---|---|
| S1701 | Payments for processing of goods |
Cover page codes you will never select
There is a third set of 23 codes in the same annexure. You will occasionally see them quoted as if they were transaction codes. They are not. They are aggregates a bank reports on the cover page of its R-Return, summing a whole fortnight.
| Code | Description |
|---|---|
| P0091 | Purchase from Reserve Bank of India (Currency-wise Totals) |
| P0092 | Purchase from other ADs in India (Currency-wise Totals) |
| P0093 | Purchase from Overseas banks & correspondents (Currency-wise Totals) |
| P0094 | debit from the vostro a/c of overseas bank or correspondents (Country-wise Totals) |
| P0095 | Aggregate Purchases at Branches (Currency-wise Totals) |
| P0100 | Exports (Totals) {N/P/D + Collection bills Realised during Fortnight + Advance received during Fortnight} (Purchases from Public against exports (Currency-wise Totals)} |
| P0144 | Purchases from Public against third country exports (Currency-wise Totals) |
| P1590 | receipts below Rs. 5 lakhs (Currency-wise Totals) |
| P1591 | Non-Exports equivalent & above Rs.5 lakhs (Currency-wise Totals) |
| S0091 | Sales to Reserve Bank of India (Currency-wise Totals) |
| S0092 | Sales to other ADs in India (Currency-wise Totals) |
| S0093 | Sales to Overseas banks & correspondents (Currency-wise Totals) |
| S0094 | credit to the vostro a/c of overseas bank or correspondents (Country-wise Totals) |
| S0095 | Aggregate Sales at Branches (Currency-wise Totals) |
| S0144 | Sales to Public against Imports into other countries (Currency-wise Totals) |
| S0190 | Imports below Rs.5 lakhs(Currency-wise Totals) |
| S0191 | Imports equivalent & above Rs.5lLakhs (Currency-wise Totals) |
| S1590 | Non-Imports payment below Rs 5 lakhs (Currency-wise Totals) |
| S1591 | Non-Imports equivalent & above Rs.5 lakhs (Currency-wise Totals) |
| P2088 | Opening Balance (Debit Balance in Mirror/Debit Balance in Vostro) |
| P2199 | Closing Balance (Debit Balance in Mirror/Debit Balance in Vostro) |
| S2088 | Opening Balance (Credit Balance in Mirror/Credit Balance in Vostro) |
| S2199 | Closing Balance (Credit Balance in Mirror/Credit Balance in Vostro) |
If a provider tells you your transaction was booked under S0190, they mean it fell below the five lakh individual reporting threshold and was reported in aggregate. It is not a description of what you bought.
Where P and S codes stop mirroring each other
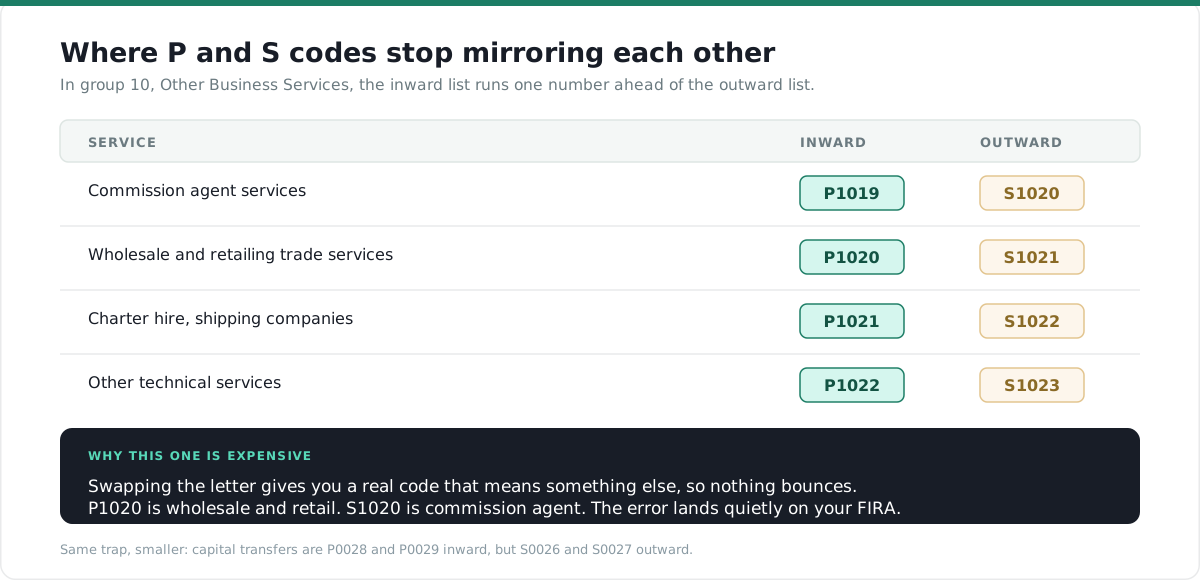
The most expensive assumption on this page is that you can take a code, swap the letter, and get the equivalent in the other direction. It works for most of the list. In group 10 it breaks, four times in a row.
Service | Inward | Outward |
Commission agent services | P1019 | S1020 |
Wholesale and retailing trade services | P1020 | S1021 |
Charter hire, shipping companies | P1021 | S1022 |
Other technical services | P1022 | S1023 |
The inward list runs one number ahead of the outward list from P1019 onward, because the two lists retired different codes. Swap the letter on any of these four and you get a real code that means something else. P1020 is wholesale and retail; S1020 is commission agent. Both exist, so nothing bounces, and the misclassification sits quietly on your FIRA.
Codes people search for that do not exist
Some codes are searched for regularly and are simply not in the current list. If a page shows you one, that page is quoting the withdrawn annexure.
Code searched | Reality |
S0222 | No outward code for postal and courier by air. Only S0223, by sea. Inward has all three. |
S1106 | No outward code for recreation and sporting activity. Inward has P1106. |
S0302 | Basic Travel Quota code retired. Use S0306. |
S0401 to S0404 | Group 04 abolished. Postal and courier moved to group 02, telecom to group 08. |
S1001 and P1001 | Merchanting moved to S0108 and P0108. |
P0106 | Retired. No replacement. |
S0604, S0606 | Folded into S0603, S0607 and S0608. |
S1404, S1406, S1407 | Replaced by S1408 to S1412. |
Choosing the right code
Three questions, in order.
Which direction is the money going? Into India is P, out of India is S. Direction is from the bank's perspective, so an exporter receiving payment uses a P code.
Is it goods, a service, income, or capital? Goods sit in group 01. Services run from group 02 to group 17. Income, meaning salary, interest, dividends and profit, sits in groups 13 and 14. Anything that changes who owns an asset is group 00.
Within the group, what did the contract actually say? This is where accuracy is won or lost. The list rewards reading your own invoice. Software consultancy and off-site software export are different codes. Advance payment and invoice settlement are different codes. Salary and consulting fees are different codes.
If nothing fits, use the group's catch-all rather than forcing a neighbouring code. P1099 and S1099 exist for that reason, and "other services not included elsewhere" is an honest answer that will not contradict your paperwork later.
What happens when the code is wrong
Not a penalty, usually. The realistic consequences are slower and more annoying than that.
The bank queries the remittance. The documents you submitted do not match what the code implies, so the transaction sits while somebody asks for a clarification. This is the most common outcome and it costs days.
Your FIRA says the wrong thing. The FIRA is the document your CA uses to support the treatment of that receipt, and an auditor or an assessing officer reads it years later with no memory of what actually happened. A software export coded as a gift is a conversation you do not want to be having in year three.
Your export obligation does not close properly. If an export receipt is coded as something other than an export receipt, it may not match against the shipping bill, which leaves an entry outstanding in the bank's reconciliation and eventually on the EDPMS side.
Correcting a code after the fact is possible, through the AD bank that handled the transaction, but it is a manual request and it is far more work than getting it right at submission.
Paying an overseas supplier?
EximPe is an RBI-authorised Payment Aggregator, Cross Border. Certificate No. 291/2026.
Purpose code and FEMA documentation are handled inside the transaction rather than chased afterwards, you get a live FX rate, and the paperwork is closed out with the payment. Built for Indian businesses paying across borders.
AD1 accounts are for Indian entities.
Frequently Asked Questions
Frequently Asked Questions
297 in the current annexure: 138 inward P codes, 136 outward S codes, and 23 cover page codes that banks use for fortnightly aggregates rather than individual transactions. Lists that say "over 150" are counting one direction, or counting the withdrawn annexure.
P is a purchase of foreign exchange by the bank, so money entering India. S is a sale by the bank, so money leaving India. The letter describes the bank's side of the trade, not yours.
For software consultancy and implementation outside a SOFTEX filing, P0802. For off-site software exports, P0807. For business and management consultancy, P1006. For advertising and market research work, P1007 or P1016. If you are employed by a foreign company rather than contracting with one, your salary is P1401.
Yes, through the AD bank that processed the transaction. It is a manual amendment request and banks treat it as an exception, so expect to explain and document the original error.
No. It is a balance of payments classification. Your tax treatment follows the Income-tax Act and the facts of the transaction. The code matters to tax indirectly, because it shapes what your FIRA says, and your FIRA is evidence.
Yes. Annex I to A.P. (DIR Series) Circular No. 84 dated 29 February 2012, RBI/2011-12/413. Be careful with the two RBI PDFs numbered 52220 and 52221 that most search results point to. Both are stamped Withdrawn.